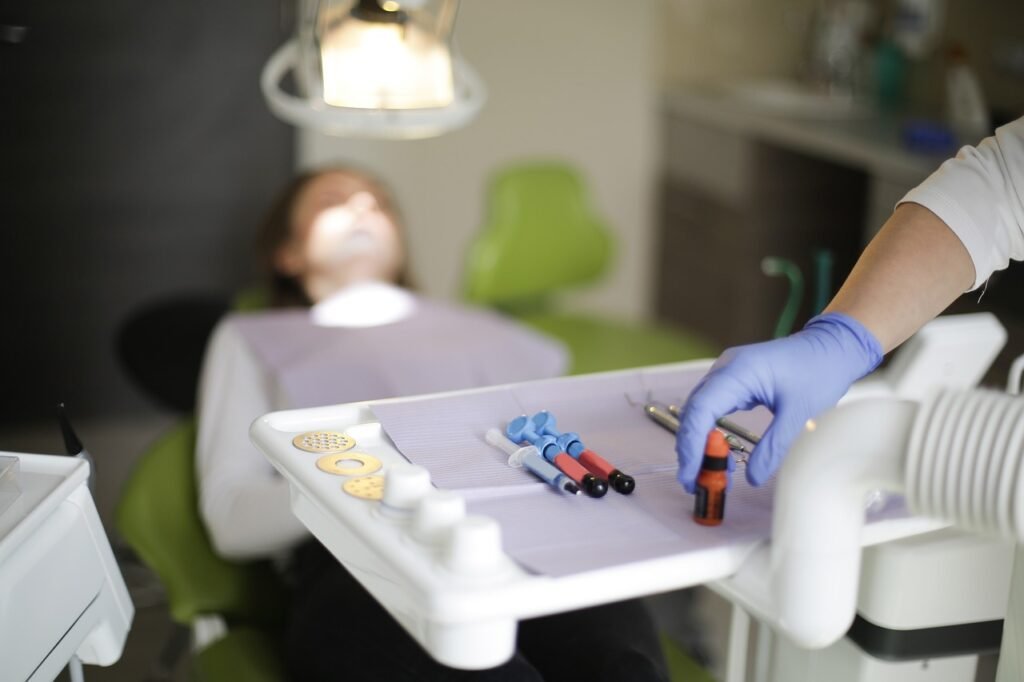
When evaluating dental insurance plans, consumers often discover that standard health policies leave a wide gap for routine cleanings, fillings, and major oral surgery. Choosing the right coverage requires understanding how monthly premiums interact with annual maximums and specific network restrictions. Unlike medical policies that focus primarily on catastrophic events, these products are structured around predictable preventative care alongside shared costs for restorative work. Navigating the market successfully means balancing anticipated dental needs against ongoing monthly expenses to avoid paying for benefits you never use. Check official resources like Healthcare.gov to understand baseline market standards before purchasing standalone policies.
Quick answer: Dental insurance plans are standalone or employer-sponsored policies designed to offset the cost of routine dental care and major restorative procedures. They typically use a tiered coinsurance structure for preventive, basic, and major services, subject to an annual maximum benefit limit.
1. Dispelling Common Myths About Dental Insurance Plans
Many buyers approach the market with misconceptions that lead to expensive surprises later. Sorting fact from fiction helps clarify what these policies actually deliver.
- Myth: Coverage works just like regular health insurance with an out-of-pocket maximum. Fact: Most dental policies feature a hard annual maximum cap, meaning the insurer stops paying after a certain dollar amount is reached each year.
- Myth: Cosmetic procedures like teeth whitening are covered under standard benefits. Fact: Cosmetic enhancements are almost universally excluded from standard dental insurance plans.
- Myth: You can sign up and immediately get major bridge work done without penalty. Fact: Waiting periods often apply to major and basic services to prevent immediate high-cost claims.
2. Who Needs Dental Insurance Plans and Who Can Skip Them
Purchasing coverage makes sense for individuals who maintain consistent preventative habits or anticipate needing restorative care. Routine bi-annual visits, cleanings, and diagnostic x-rays generally cost less out-of-pocket when spread across predictable monthly premiums, especially for families with growing children who require sealants and orthodontia evaluations.
Conversely, adults with excellent oral health who possess substantial emergency savings might decide to bypass commercial dental insurance plans entirely. Paying cash for routine cleanings twice a year can sometimes cost less than twelve months of cumulative premium payments, provided no unexpected root canals or crowns arise. Reviewing your personal dental history helps determine if self-funding is a viable alternative to smart financial management.

3. Breaking Down Premiums, Deductibles, and Annual Limits
Every policy operates on a financial triad consisting of monthly premiums, annual deductibles, and yearly maximum payout limits. The premium represents your fixed monthly cost to keep the policy active, while the deductible is the initial out-of-pocket amount you must pay before the insurer contributes to your care. Once those thresholds are met, the plan pays a designated percentage of approved charges up to the annual limit.
Annual maximums typically hover between one thousand and two thousand dollars per year. Any dental expenses exceeding that ceiling become entirely the responsibility of the policyholder. Understanding these boundaries ensures you do not schedule expensive multi-stage procedures without calculating your exact remaining benefit balance.
Always verify whether your preferred dentist participates in the specific network tier associated with your policy, as out-of-network providers can bill you for the difference between their standard fees and the insurer’s allowed amounts.
4. Comparing Coverage Tiers and Benefit Levels
Policies are generally categorized by how deeply they subsidize different types of dental care. The table below outlines the three main coverage tiers found across the market. For a related angle, see our guide on dental and vision insurance plans. A closely related read is our piece on medicare supplement plans.
Evaluating these tiers helps you match your actual clinical needs with the appropriate plan structure.
| Coverage Tier | What It Covers | Cost Impact | Best For |
|---|---|---|---|
| Basic (Preventive) | Cleanings, exams, routine x-rays | Low monthly premium, high insurer share | Individuals with healthy teeth needing only maintenance |
| Standard | Fillings, simple extractions, root canals | Moderate premium, shared coinsurance split | People anticipating typical restorative fillings |
| Comprehensive | Crowns, bridges, dentures, major surgery | Highest monthly premium, broader coverage | Patients requiring extensive restorative dental work |
5. Major Cost Drivers Impacting Your Monthly Rates
Several variables influence how much you will pay for dental insurance plans on the open market. Geographic location plays a massive role, as regional dental labor costs and local cost-of-living indexes dictate baseline pricing structures. Plans in metropolitan areas with higher operating expenses typically command higher premiums than identical policies in rural counties.
The age of the insured individual and the number of covered family members also shift the pricing scale significantly. Younger adults generally enjoy lower rates, while older demographics face higher premiums due to the increased statistical likelihood of needing major restorative treatments. Additionally, choosing an exclusive network restriction like a dental health maintenance organization usually reduces your monthly cost compared to a traditional preferred provider organization model.
6. Identifying Common Policy Exclusions and Waiting Periods
Reading the fine print prevents unpleasant surprises when you submit your first claim. Most dental insurance plans enforce waiting periods ranging from six to twelve months for basic and major services, meaning you pay premiums before receiving financial help for crowns or bridges. Pre-existing conditions clauses may also exclude missing teeth that were lost before your coverage effective date.
Orthodontic care, temporomandibular joint treatment, and experimental procedures are routinely excluded from standard policies. Knowing these exclusions ahead of time allows you to budget accurately for specialized care that falls outside your network boundaries. For broader financial planning insights, explore topics related to family financial protection and long-term asset strategies.

7. Step-by-Step Guide to Shopping for Policies
Finding the right coverage involves a systematic approach to evaluating your options. Follow these steps to secure the ideal policy for your household.
- Audit your recent dental history and estimate your anticipated dental needs for the upcoming year.
- Contact your current dentist to confirm which specific networks and carrier plans they accept.
- Obtain quotes from multiple providers, noting differences in deductibles, annual limits, and waiting periods.
- Calculate your total projected annual cost by adding all twelve monthly premiums to your expected out-of-pocket expenses.
- Enroll in the chosen plan during an open enrollment period or qualifying life event window.
8. Fairly Comparing Quotes Across Different Providers
Apples-to-apples comparisons are essential when reviewing dental insurance plans from competing companies. Look past the monthly premium figure to examine the underlying coinsurance percentages for basic and major care. A policy with a slightly higher monthly rate might actually save you money if it offers an eighty percent coinsurance split instead of a fifty percent split for restorative fillings.
Check the network size and geographic distribution of participating dentists in your area. A cheap policy with only a handful of participating providers within a fifty-mile radius offers little practical value if your preferred clinic refuses to accept it. Always review independent financial ratings from agencies like AM Best to ensure the insurance carrier maintains strong financial stability.
9. How the Claims and Reimbursement Process Works
Understanding how claims move from the dentist’s chair to the insurance company prevents billing confusion. Most in-network providers submit claims directly to the insurer on your behalf, handling the paperwork electronically. You will receive an explanation of benefits detailing what the dentist charged, what the plan paid, and your remaining patient balance. You may also want to read about medicare supplement plans. You may also want to read about choose international travel medical insurance.
If you visit an out-of-network provider, you may need to pay the entire bill upfront and submit a manual claim form along with itemized receipts for reimbursement. The insurer then sends a check directly to you based on their allowed fee schedule. Keeping meticulous records of every transaction ensures you can quickly resolve any discrepancies or denied claims.
10. Proven Methods to Lower Your Out-of-Pocket Dental Expenses
Minimizing your total dental expenditure requires strategic planning beyond simply paying for monthly premiums. The table below compares popular savings methods by their required effort, savings potential, and associated trade-offs.
Combining insurance coverage with these alternative strategies helps optimize your overall dental budget.
| Savings Method | Effort Required | Savings Potential | Trade-Off |
|---|---|---|---|
| Flexible Spending Account (FSA) | Moderate | High (pre-tax dollars) | Use-it-or-lose-it rule applies annually |
| Dental School Clinics | High | Very High | Appointments take significantly longer |
| Discount Dental Plans | Low | Moderate | Not insurance; requires paying cash fees |
To conclude, evaluating dental insurance plans carefully ensures you secure the right balance of routine preventive care and major restorative protection without overpaying for unnecessary extras.
Frequently Asked Questions About Coverage
What happens if I exceed my annual maximum benefit?
Once you reach the annual dollar limit set by your policy, the insurance company stops paying for any additional dental work for the remainder of that calendar year. You become entirely responsible for one hundred percent of all further dental costs until the next benefit period begins. Scheduling major procedures across two calendar years is a common strategy to maximize available benefits.
Are waiting periods waivable if I had previous coverage?
Many insurance carriers offer waiting period credit or waivers if you can provide proof of continuous prior dental coverage with no break exceeding sixty days. You must submit your previous certificate of coverage during the application process to qualify. Always ask the broker or carrier representative about portability rules before enrolling.
Can I purchase a policy as an individual, or must it be through an employer?
You can easily purchase individual dental insurance plans directly from private insurance companies or through state and federal insurance marketplaces. Individual plans provide flexibility if your employer does not offer benefits or if you are self-employed. However, employer-sponsored group plans often feature lower premiums and more lenient underwriting terms.
Do these policies cover cosmetic whitening and veneers?
Standard dental insurance plans strictly exclude cosmetic treatments such as teeth whitening, cosmetic bonding, and elective porcelain veneers. Policies only cover procedures that are deemed medically and clinically necessary to restore oral health and function. Reviewing the contract exclusions list before booking elective procedures prevents unexpected out-of-pocket bills.
What is the difference between an HMO and a PPO dental plan?
An HMO plan requires you to select a primary dentist within a specific network and generally offers no coverage for out-of-network care. A PPO plan provides greater flexibility by allowing you to visit any dentist, though staying within the preferred network reduces your out-of-pocket costs. PPOs usually feature higher monthly premiums in exchange for that provider flexibility.
How do deductibles apply to routine preventive cleanings?
In most dental insurance plans, routine preventive services such as bi-annual cleanings, exams, and diagnostic x-rays are exempt from the annual deductible. This means the insurer begins paying their coinsurance share immediately for preventative care without requiring you to meet the deductible first. Deductibles typically apply only to basic and major restorative treatments.
Related Guides
If you want to keep digging, see how we research our guides, our life insurance picks. For insurer financial strength ratings, go to A.M. Best.
Note: we are not licensed agents, and nothing here replaces advice from one. Examples use rounded, illustrative numbers; your own quotes will differ.